
UAE Business Finance Guide
Business Loan in UAE: Requirements, Eligibility & Documents
A practical guide to business loans in the UAE for established SMEs, small businesses and startups, including bank-loan and working-capital options, what lenders may assess, the documents you may need, current lender examples and how your company's credit history can affect an application.
There is no single UAE-wide minimum turnover, trading-history requirement, loan amount or approval timeline for a business loan. An established SME, a small business seeking working capital and a newly formed startup can face very different eligibility rules. The lender, product, company profile, financial performance, credit history, funding purpose and any security or guarantees required all matter.
This guide is general information rather than a financing offer or guarantee of approval. Banks and finance providers set their own eligibility, pricing, documentation and credit requirements, which can change.

Types of Business Finance Available in the UAE
The first decision is not which bank to approach. It is what type of finance matches the purpose of the funding. A business that needs to buy equipment has a different financing need from one trying to bridge a short gap between issuing an invoice and receiving payment.
Term loans
A term loan provides an agreed amount that is repaid over a defined period. Businesses may use term finance for expansion, fit-out, equipment, technology, acquisitions or other planned expenditure. The facility may be secured or unsecured depending on the product and borrower profile.
Working-capital facilities and overdrafts
Working-capital finance is designed to support normal operating cash flow. It may be appropriate where a healthy business has timing gaps between paying suppliers, salaries or other costs and receiving customer payments.
Asset and equipment finance
These facilities are connected to assets such as machinery, vehicles, equipment or commercial property. The financed asset may form part of the lender's security package. As a current example, RAKBANK publishes asset-based finance of up to AED 35 million, with funding of up to 90% LTV/FTV across eligible vehicles and heavy equipment. Its published quick-apply criteria show a minimum business length of one year and minimum six-month turnover of AED 500,000 for that route.
Trade finance
Importers, exporters and trading businesses may require letters of credit, guarantees, trust-receipt facilities or other trade-finance products rather than a conventional cash loan.
Invoice and receivables finance
A business with qualifying invoices or receivables may be able to access funding against money due from customers rather than waiting for the full payment cycle.
Islamic business finance
UAE banks also provide Sharia-compliant business finance. Structures can include Murabaha and Ijara, among others. The contractual structure differs from a conventional interest-bearing loan, so compare the complete commercial terms rather than assuming the products are identical.
A larger advertised maximum does not mean that product is the best match. Repayment structure, security, fees, eligibility and how the funds will actually be used are equally important.
Business Loan Eligibility in the UAE for SMEs & Startups
There is no universal eligibility checklist that applies to every UAE bank and financing product. Published criteria vary considerably, but lenders commonly examine several underlying areas when deciding whether a company can support additional debt.
Company status
A lender may check the trade licence, legal form, shareholders, authorised signatories, business activity and whether the company is mainland or free-zone based.
Trading history
Some products require a minimum operating period. Others, particularly development or startup programmes, may assess earlier-stage companies using different criteria.
Turnover and cash flow
Lenders may review turnover, account activity, profitability, margins, existing obligations and the company's ability to make repayments.
Credit history
Company credit behaviour and, where relevant to the facility, information relating to owners or guarantors can affect the lender's risk assessment.
Business sector
Sector, customer concentration, supplier dependence, geographic exposure and the stability of the underlying business model can all matter.
Security and guarantees
Depending on the facility, the lender may request collateral, assignment of receivables, a corporate guarantee, a personal guarantee or another form of security.
This is why statements such as “every UAE business needs AED 1 million turnover” or “all companies need two years of trading” are misleading. Those figures may describe a particular product, but they are not UAE-wide lending rules.
UAE SME regulation: the Central Bank's Small to Medium Sized Enterprises (SME) Customer Protection Regulation C 2/2026 took effect on 13 September 2026 and replaced the previous SME Market Conduct Regulation C 1/2021.
The framework applies to Central Bank-licensed banks and finance companies when providing financial products or services to SME customers. It includes requirements concerning responsible financing, disclosure and transparency, access to financial products and services, complaint handling and support for SME customers in financial difficulty. It does not oblige a lender to approve a particular application.
Current UAE Business Loan Examples
Published lender products are useful for understanding how widely eligibility, maximum facilities and repayment periods can vary. The examples below are not a ranking and are not directly comparable because the underlying products, security structures and customer profiles differ.
| Provider | Example product | Published headline | Important context |
|---|---|---|---|
| Emirates Development Bank | Startup financing | Up to AED 2 million; tenure up to 72 months | For qualifying startups, with assessment including business and qualitative factors and a focus on EDB strategic sectors. |
| RAKBANK | Business Loan | Up to AED 5 million; repayment up to 60 months | Advertised as collateral-free. Final eligibility, amount and terms remain subject to the bank's assessment. |
| Emirates NBD | Small Business Loan | AED 50,000 to AED 300,000; tenure up to 36 months | One of several SME financing routes published by the bank; other facilities have different limits and structures. |
| Mashreq | Merchant / business lending | Published merchant lending limits up to AED 4 million and up to 48 months | Published business-loan guidance also states that newly registered businesses must generally have been operational for more than two years for the relevant products. |
| ADCB | Retail Business Loan | Up to AED 250,000; repayment up to four years | The published product requires at least two years in operation and minimum turnover of AED 500,000. |
Product information above reflects lender-published information rechecked in September 2026. Limits, eligibility, fees and terms can change. Always check the current product information, Key Facts Statement and final facility offer directly with the lender.
The comparison demonstrates why it is better to match your company to a suitable facility than to apply repeatedly based only on the highest advertised loan amount.
Documents Required for a Business Loan in the UAE
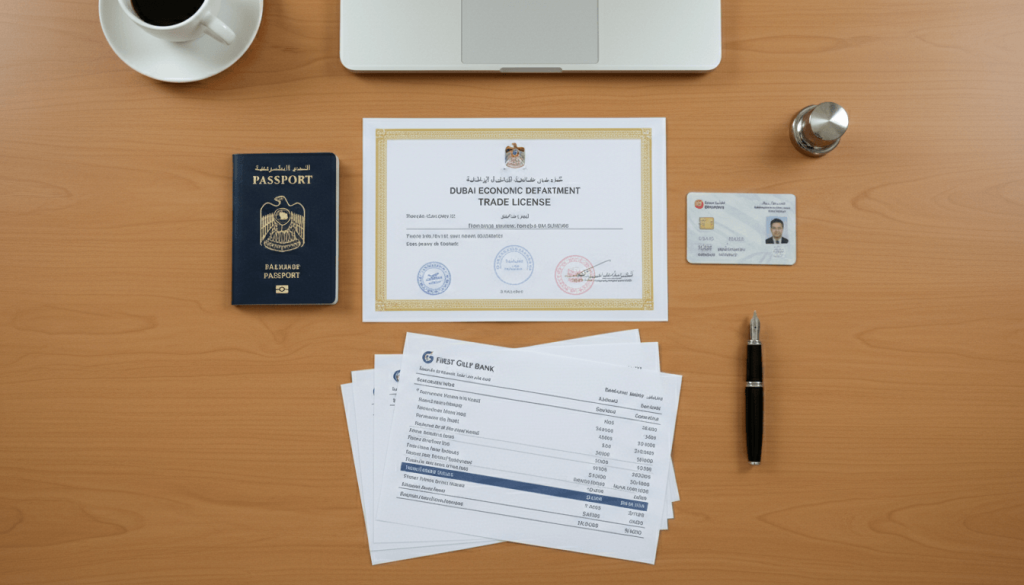
Document requirements differ according to the lender and facility, but a well-prepared application normally needs to establish three things: who owns and controls the company, how the business operates, and whether its finances support the proposed borrowing.
Company and KYC documents
- Valid UAE trade licence
- Memorandum or Articles of Association, where applicable
- Shareholder or partner information
- Passport, Emirates ID and residency records requested for relevant owners or signatories
- Power of Attorney or signing-authority records, where applicable
- Company address or premises evidence where requested
Financial information
- Business bank statements for the period requested by the lender
- Audited financial statements where required
- Management accounts where accepted or requested
- VAT registration and returns where applicable
- Details of existing loans and financial obligations
- Cash-flow forecasts for facilities where forward-looking performance matters
Commercial evidence
- Business profile explaining the company's activities
- Customer or supplier contracts where relevant
- Invoices, purchase orders or receivables supporting the funding need
- Business plan for startup, expansion or project-based funding where requested
- Equipment quotations, property documents or other asset records for secured finance
Use consistent company names, licence details, ownership information and financial figures throughout the application. A lender may ask for additional evidence, but a coherent starting file makes follow-up easier.
How AECB Credit History Can Affect a UAE Business Loan
Credit information is an important part of financing decisions. Etihad Credit Bureau provides credit reports and credit scores for UAE companies as well as individuals.
A company's credit report can include its credit score, payment history, financial obligations and overall creditworthiness. This gives the business itself—and authorised credit providers—a clearer picture of existing credit behaviour.
What should a business check before applying?
- Whether existing credit facilities are shown correctly
- Whether payment history reflects the company's actual conduct
- Whether outstanding liabilities are understood before new borrowing is requested
- Whether any incorrect information should be raised through the appropriate correction process
A higher credit score generally represents a lower perceived credit risk, but there is no universal minimum AECB score that guarantees approval for every UAE business loan. The lender remains responsible for its own credit decision.
Depending on the facility and guarantee structure, a lender may also assess relevant shareholders, authorised signatories or guarantors rather than looking only at the company's report.
How to Get a Business Loan in the UAE: Step by Step
A better application starts before the application form. The aim is to choose a facility that matches the funding need and present enough evidence for a lender to understand the company, repayment source and risks.
Define exactly why you need the money
Separate working-capital needs from long-term asset purchases, expansion, project finance or invoice-related cash flow. Define the amount, intended use and realistic repayment source.
Check your company and banking records
Ensure the licence, ownership records, signing authorities and corporate documents are consistent. Review the business bank account and existing liabilities before approaching a lender.
Review your credit position
Understand the company's existing credit obligations and consider reviewing its Etihad Credit Bureau information before submitting a major financing application.
Shortlist suitable products
Compare actual eligibility—not only the advertised maximum amount. Consider trading-history rules, turnover requirements, security, sector restrictions, repayment structure and funding purpose.
Prepare the application pack
Combine the legal, KYC, financial and commercial evidence into one coherent file. Explain what the business does, why the money is required and how the proposed debt can be serviced.
Respond to lender questions consistently
Credit and compliance teams may request updated statements, contracts, ownership clarification or other evidence. Make sure later answers remain consistent with the original application.
Review the final offer—not just the monthly repayment
Check the approved amount, rate or profit structure, fees, repayment schedule, early-settlement provisions, guarantees, collateral, insurance and reporting obligations before accepting the facility.
If your company is still being established, begin with the structure itself. First Elite Global's business setup in Dubai guidance explains how activity, jurisdiction, ownership and operational requirements fit together before banking and finance are considered.
Can a Startup Get a Business Loan in the UAE?
Yes, startup financing exists in the UAE, but a newly formed company should not assume it qualifies for the same products as an established SME.
Some commercial bank products explicitly require an operating track record. For example, current ADCB and Mashreq product information includes two-year operating requirements for particular business-finance products. RAKBANK's current Business Loan quick-apply criteria use a shorter published minimum of one year in business, together with minimum six-month turnover of AED 300,000. That still means a newly incorporated company should not assume it qualifies for a standard commercial bank loan immediately.
Development financing can follow a different model. Emirates Development Bank currently publishes startup financing of up to AED 2 million for qualifying businesses, with tenors of up to 72 months. EDB states that its startup assessment can consider financial and qualitative evaluation and focuses support around strategic sectors.
For an early-stage company, focus on building evidence
- Obtain the correct trade licence and company structure.
- Use a dedicated corporate bank account for business activity.
- Record founder capital and other funding clearly.
- Maintain understandable invoices, contracts and transaction records.
- Prepare realistic financial projections rather than aggressive forecasts.
- Investigate startup or development programmes whose eligibility matches the company.
The important distinction is that “startup finance exists” does not mean that a pre-revenue company is automatically eligible. Every provider retains its own underwriting and approval process.
Business Loan Costs, Rates, Tenure and Security
There is no single UAE business-loan interest rate. Pricing depends on the product, lender, company risk profile, facility size, security, repayment period and market conditions.
Interest or profit rate
Conventional facilities may use fixed or variable pricing. Some variable facilities can reference a benchmark such as EIBOR plus a lender margin. Islamic facilities use an agreed Sharia-compliant profit structure instead of conventional interest.
Processing and arrangement fees
A facility may include processing, arrangement, documentation or other lender fees. Do not assess affordability from the headline rate alone.
Security-related costs
Secured borrowing may involve valuation, insurance, registration or other costs connected with the asset or security package.
Early repayment
Check whether partial prepayment or full early settlement triggers a fee and whether the facility has any restrictions around when repayment can be made.
Tenure
Published UAE products range from comparatively short SME facilities to much longer secured or capital-expenditure financing. There is therefore no single “standard” business-loan tenure.
Guarantees and collateral
Depending on the facility, security may include property, equipment, receivables, deposits, corporate guarantees or personal guarantees. Some products are advertised as collateral-free, but that does not mean the lender performs no credit assessment or imposes no other conditions.
Before accepting finance, review the Key Facts Statement and facility offer and understand the rate or profit calculation, fees, insurance, security, repayment schedule and early-settlement terms.
How to Improve Your Chances of Approval
No preparation can guarantee a business loan, but a clear and internally consistent application makes it easier for a lender to assess the company.
- Keep business and personal finances separate. Use the company account for genuine company activity.
- Keep company records current. Licence, ownership and authorised-signatory information should agree.
- Understand existing debt. Know current repayment commitments before requesting another facility.
- Explain unusual transactions. Large transfers, cash activity or irregular movements may require context.
- Ask for a defensible amount. Connect the request to an identifiable funding requirement and repayment source.
- Use realistic forecasts. Assumptions should be explainable using the company's actual business model.
- Prepare contracts and invoices. Evidence of customers, suppliers or pipeline can help explain the commercial position.
- Check credit information. Resolve genuine inaccuracies through the appropriate credit-data correction route.
- Apply selectively. Confirm that your company fits the published product criteria before submitting multiple applications.
If the business does not yet have a suitable operating account, review the requirements for corporate bank account opening support in the UAE before assuming financing should be the first banking step.
Where First Elite Global Can Help
A lender decides whether to approve a business loan. First Elite Global is not able to guarantee financing, a particular loan amount, a rate or an approval date.
Where the financing process depends on the underlying UAE company, however, First Elite Global can support relevant company-formation and banking-readiness work. This can include reviewing the intended UAE business structure, coordinating formation documents and helping a company prepare for a corporate bank-account application within the agreed service scope.
Still preparing the company before approaching a lender?
Start with the legal structure, licensed activity, ownership records and banking route. Those foundations can affect the evidence a bank later asks to review.
Explore UAE business setup or corporate banking preparation.
Frequently Asked Questions About Business Loans in the UAE
What is the minimum turnover required for a business loan in the UAE?
There is no single UAE-wide minimum turnover. Individual products set their own requirements. For example, ADCB currently publishes a minimum AED 500,000 turnover requirement for its Retail Business Loan, while other providers use different criteria or financing structures.
How many years must a UAE company be trading before applying?
It depends on the product. Some commercial bank facilities currently require around two years of operations, while qualifying startup programmes and development financing may consider earlier-stage companies using different underwriting criteria.
Can a one-year-old business qualify for a UAE business loan?
Potentially, depending on the lender and the company's financial profile. RAKBANK's current published Business Loan criteria show a minimum business length of one year and minimum six-month turnover of AED 300,000, while ADCB and Mashreq publish two-year operating requirements for certain business-loan routes. Meeting a published minimum does not guarantee approval.
Can a new company get a startup business loan in the UAE?
Potentially. New companies may not meet the trading-history rules used by many traditional bank products, but development and startup financing programmes exist. Emirates Development Bank, for example, publishes financing for qualifying startups. Eligibility is still assessed case by case.
Is there a minimum AECB credit score for a UAE business loan?
There is no universal score that guarantees approval across all UAE lenders. Credit history is one part of a wider assessment that can include financial performance, existing liabilities, business activity, repayment capacity, security and other lender-specific criteria.
What documents are usually required?
Common requests include a valid trade licence, incorporation documents, shareholder and signatory identification, business bank statements and financial information. Contracts, VAT records, projections, collateral evidence or other documents may be required depending on the facility.
How long does business-loan approval take in the UAE?
There is no reliable universal approval period. Timing depends on the lender, product, requested amount, completeness of the application, credit assessment, compliance review, security and any additional documentation required.
Do I need a UAE business bank account before applying?
Many established-business lending products rely heavily on business bank statements and account activity, so an operating corporate account is often important. Requirements can differ for startup, development or asset-backed facilities, so check the specific lender's criteria.
Can a foreign-owned UAE company apply for a business loan?
Foreign ownership does not automatically prevent a UAE company from seeking business finance. The lender will assess the specific entity, owners, authorised signatories, residency position, business activity, financial profile and any guarantee or security requirements that apply to its product.
Are Sharia-compliant business finance options available?
Yes. UAE Islamic banks and Islamic banking divisions offer business-finance structures designed to comply with Sharia principles. The exact structure, profit calculation, asset involvement and repayment terms depend on the facility.
Can First Elite Global guarantee that my business loan will be approved?
No. The bank or finance provider makes the credit decision. First Elite Global can assist with relevant UAE company-setup, documentation and corporate banking-readiness services within the agreed scope, but cannot guarantee a loan, amount, rate or approval timeline.
Final Checklist Before You Apply
A business loan in the UAE is easier to evaluate when you separate universal fundamentals from lender-specific rules. There is no single turnover figure, trading period, interest rate or approval time that applies to every business.
- Define the funding purpose and amount.
- Choose the appropriate type of finance.
- Check the specific lender's published eligibility.
- Review company and Etihad Credit Bureau information.
- Prepare legal, KYC, banking and financial records.
- Understand all existing financial obligations.
- Compare the total facility cost and security terms.
- Read the lender's Key Facts Statement and final offer before signing.
For startups, the process may begin with the company structure and banking history rather than a conventional commercial loan. For established businesses, the priority is normally demonstrating a credible funding purpose, clear financial position and sustainable repayment capacity.
Preparing Your UAE Company for Banking or Finance?
If the next step depends on getting the UAE company structure, licence, corporate records or banking preparation in order, First Elite Global can help define the relevant setup and documentation route. Financing decisions remain with the bank or finance provider.
